Banking review
Direct Bank Feed vs. CSV Statement Import: Which Gives You More Control?
Direct feeds prioritize continuous convenience; CSV imports prioritize deliberate, bounded review. Learn the tradeoffs before choosing a bank-data workflow.
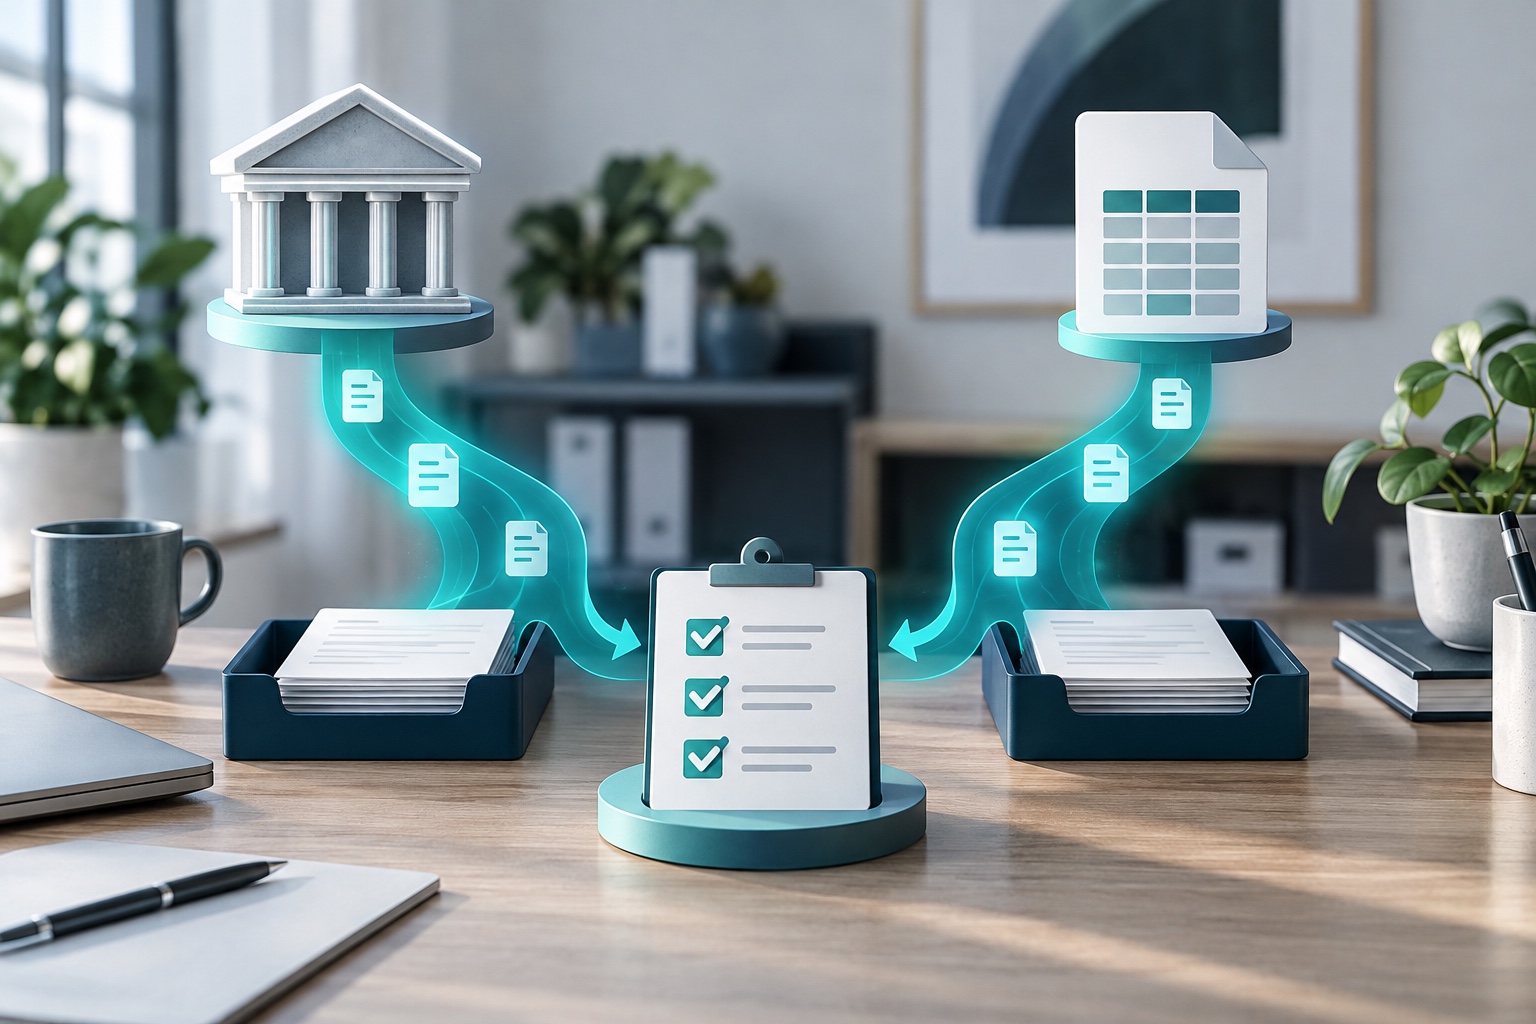
A direct bank feed and a CSV statement import can both reduce manual entry. They do it in different ways.
A bank feed aims to bring transactions into software continuously. A CSV workflow asks the owner to download a statement file and import a defined period deliberately.
Neither method is automatically better for every Business. The right choice depends on the value you place on speed, predictability, review, account coverage and control over when financial data moves.
What is a direct bank feed?
A direct bank feed connects financial-account data to another application. Depending on the bank, provider and connection method, transactions may appear automatically or after synchronization.
Potential advantages include:
- less manual downloading;
- more frequent transaction visibility;
- faster categorization or matching workflows;
- easier day-to-day monitoring; and
- reduced risk of forgetting an entire statement period.
Potential limitations include:
- connection interruptions;
- delayed or missing transactions;
- duplicate transactions after reconnection;
- inconsistent descriptions;
- limited historical coverage;
- unsupported accounts or institutions;
- consent and credential concerns; and
- dependence on several providers remaining compatible.
A feed is a delivery channel. It does not prove that every transaction was imported correctly or categorized appropriately.
What is a CSV statement import?
CSV stands for comma-separated values. Many financial institutions allow customers to download account activity in a spreadsheet-like file.
In a deliberate import workflow, the owner:
1. signs in to the financial institution directly;
2. selects the account and exact period;
3. downloads the file;
4. stores the source securely;
5. imports it into the review system;
6. checks the columns and date range; and
7. reviews proposed matches or new records.
Potential advantages include:
- clear control over the account and period imported;
- a source file that can be archived;
- predictable monthly timing;
- independence from a continuous connection;
- easier re-performance of a bounded review; and
- compatibility with accounts that do not support a feed.
Potential limitations include:
- manual downloading;
- inconsistent bank file formats;
- duplicate imports if the same period is uploaded twice;
- missing activity when the selected date range is wrong;
- spreadsheet date and decimal-format issues; and
- a longer delay between a transaction and its review.
CSV is not automatically safer or more accurate. It is simply a more deliberate transfer method.
Convenience versus control
The main difference is cadence.
With a feed, the system repeatedly requests or receives new data. With CSV, the owner initiates a bounded import for a known account and period.
Choose a feed when continuous visibility materially improves the workflow and the supported connection is reliable.
Choose CSV when a monthly or weekly batch is acceptable and you value a source file, a clear cutoff and less dependence on connection uptime.
Some Businesses use both: feeds for regular monitoring and official statements or CSV files for month-end completeness checks.
Security and consent questions
Ask how the connection works.
Important questions include:
- Does the application redirect you to the financial institution for authorization?
- Does it ask you to share online-banking credentials directly?
- Which accounts and data fields are accessible?
- How long does consent last?
- How can access be revoked?
- Which third parties process the data?
- What happens after the connection is removed?
Canada’s consumer-driven banking framework is evolving. Government guidance distinguishes secure API-based data sharing from screen scraping, where customers provide banking credentials to another service. Confirm the current connection method and provider status rather than assuming every “bank feed” uses the same model.
With CSV, the primary privacy question moves to file handling. Download statements only on trusted devices, store them securely and delete unnecessary working copies.
Reliability and completeness
Continuous does not mean complete.
For a direct feed:
- compare the opening and closing period with the official statement;
- look for gaps after reconnection;
- review duplicates;
- verify pending versus posted transactions; and
- investigate changed transaction descriptions.
For a CSV import:
- confirm the account number without exposing it in shared files;
- verify the start and end dates;
- confirm opening and closing balances when available;
- map date, description, debit and credit columns correctly;
- prevent overlapping imports; and
- retain the original file for re-performance.
Neither method removes the need for reconciliation.
Matching is not the same as deciding
Imported bank activity may be matched to existing receipts or expense records. Software may also suggest categories or create draft transactions.
Review before confirming:
- Does the amount match?
- Is the date difference reasonable?
- Is the currency correct?
- Does the source document support the payment?
- Is the transaction for the selected Business?
- Is it an expense, transfer, refund, owner contribution or repayment?
- Has it already been recorded?
An unmatched statement line is an exception to investigate. It should not automatically become an expense merely to clear the list.
Which method fits your Business?
A direct feed may fit when:
- transaction volume is high;
- frequent visibility matters;
- your institution and account are reliably supported;
- your team understands the consent model; and
- you still perform statement-based month-end checks.
CSV import may fit when:
- monthly review is sufficient;
- you operate low- or moderate-volume accounts;
- you want a deliberate import boundary;
- the account lacks reliable feed support;
- you prefer not to maintain a continuous connection; or
- you need to re-perform a review from an archived source file.
A hybrid may fit when:
- feeds support daily awareness;
- statements provide the official period boundary; and
- CSV is a fallback when a connection is interrupted.
A safer CSV import routine
1. Download from the financial institution directly.
2. Select one Business, account and exact period.
3. Save the untouched source file in a private folder.
4. Inspect headers and date formats before import.
5. Confirm that the system detects a repeated file or overlapping period.
6. Review proposed matches before accepting them.
7. Investigate every unmatched item.
8. Compare the final result with the statement.
9. Record who completed the review and when.
Where SilaTrail fits
SilaTrail uses a review-first statement-import workflow rather than a continuous direct bank feed. Owners import statement data for a selected Business and review proposed matches and exceptions.
SilaTrail does not connect directly to bank accounts, move money or guarantee that a CSV file is complete. The owner remains responsible for selecting the correct source file and reviewing the result.
This approach is a fit for owners who prefer a bounded, deliberate monthly workflow. Businesses that require continuous bank synchronization may be better served by a broader accounting platform or another specialized tool.
Sources and further reading
- CRA: Business records
- Financial Consumer Agency of Canada: Open banking
- Department of Finance Canada: Consumer-driven banking framework update