Banking and reconciliation
How to Reconcile a Bank Statement for a Small Business
Use a period-by-period workflow to match statement activity, existing records and supporting evidence without creating duplicates.
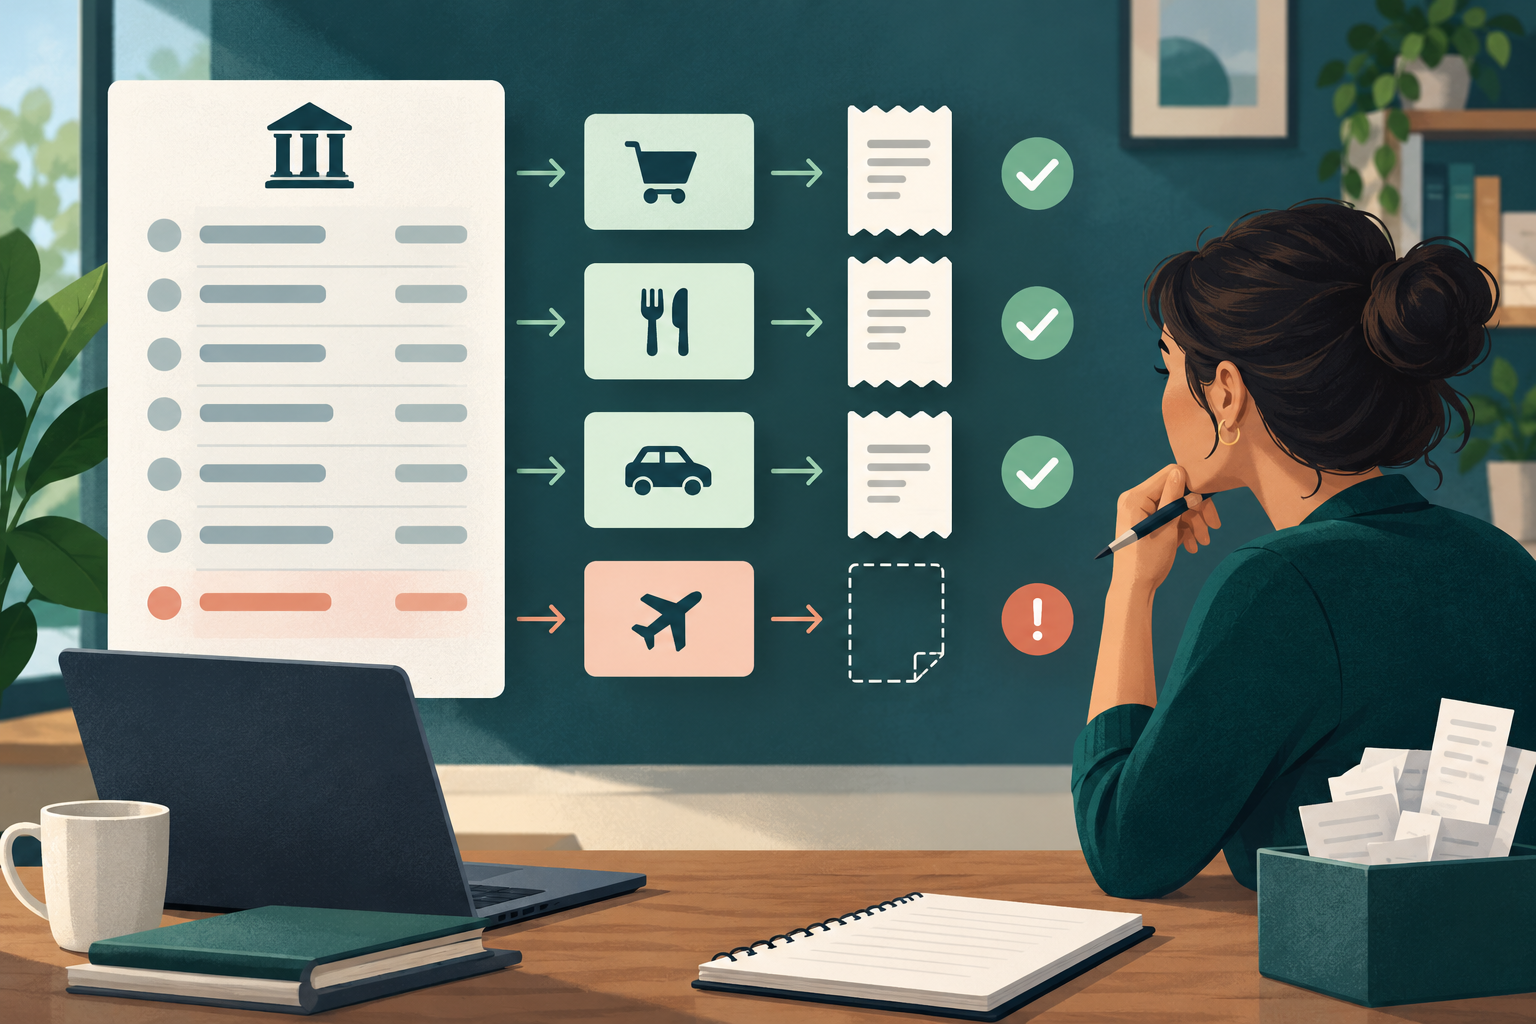
Bank reconciliation compares a financial institution's statement with the Business's recorded transactions for the same account and period. The goal is to explain every difference without inventing transactions or changing dates to force a balance.
Start with the exact statement
Choose one Business, one account and one statement period. Record the statement opening date, closing date, opening balance, closing balance and currency.
Confirm that the account belongs to the selected Business. Do not combine a personal account or another Business's statement into the same reconciliation.
Check the opening point
The opening balance should connect to the prior reconciliation or prior statement. If it does not, stop and investigate before matching the current month. Carrying an unexplained opening difference forward makes every later review harder.
Match recorded transactions
Work through the statement line by line. For each entry, look for an existing expense, income item, invoice payment, owner transaction or transfer.
Use bank statement matching to link the bank line to the existing record. Matching should not create a second expense or second sale.
Confirm the amount, currency, date range and source. Posting dates may differ from purchase dates, so retain both when they are relevant.
Classify exceptions carefully
Common exceptions include:
- recorded transaction not yet on the statement;
- statement line not yet in the Business records;
- transfer between owned accounts;
- bank fee or interest;
- refund, reversal or returned payment;
- duplicate entry;
- personal or wrong-Business transaction;
- unexplained difference.
Do not force an exception into income or expense just to complete the checklist. Assign an owner and next action.
Verify supporting documents
Open receipts, invoices and payment evidence for material or unusual transactions. The statement proves movement through the account, but it may not show the business purpose or all invoice details.
Use receipt capture to connect evidence to the correct transaction.
Complete the reconciliation record
A complete record should show:
1. Business, account and period;
2. statement opening and closing balances;
3. matched and unmatched counts;
4. listed differences;
5. reviewer and review date;
6. unresolved items and next actions.
Preserve later corrections in the audit history.
The CRA says businesses should keep bank statements, duplicate deposit slips, cancelled cheques and supporting source documents. See Business records and Keeping Records.
Frequently asked questions
Must every statement line become an expense or income record?
No. Transfers, owner contributions, repayments, refunds and corrections require their own treatment.
What if the closing balance does not agree?
Review the opening balance, missing statement pages, unmatched entries, duplicate records and signs or currencies. Keep the difference unresolved until evidence explains it.
Can I reconcile several accounts together?
Reconcile each account separately, then review consolidated Business totals afterward.
Does reconciliation prove the accounting is correct?
No. It confirms that recorded activity can be compared with the statement. It does not certify categories, tax treatment or financial statements.