Business records
How to Prepare Accountant-Ready Records Every Month
A repeatable monthly process that turns scattered evidence into a complete, reviewable package for a bookkeeper or accountant.
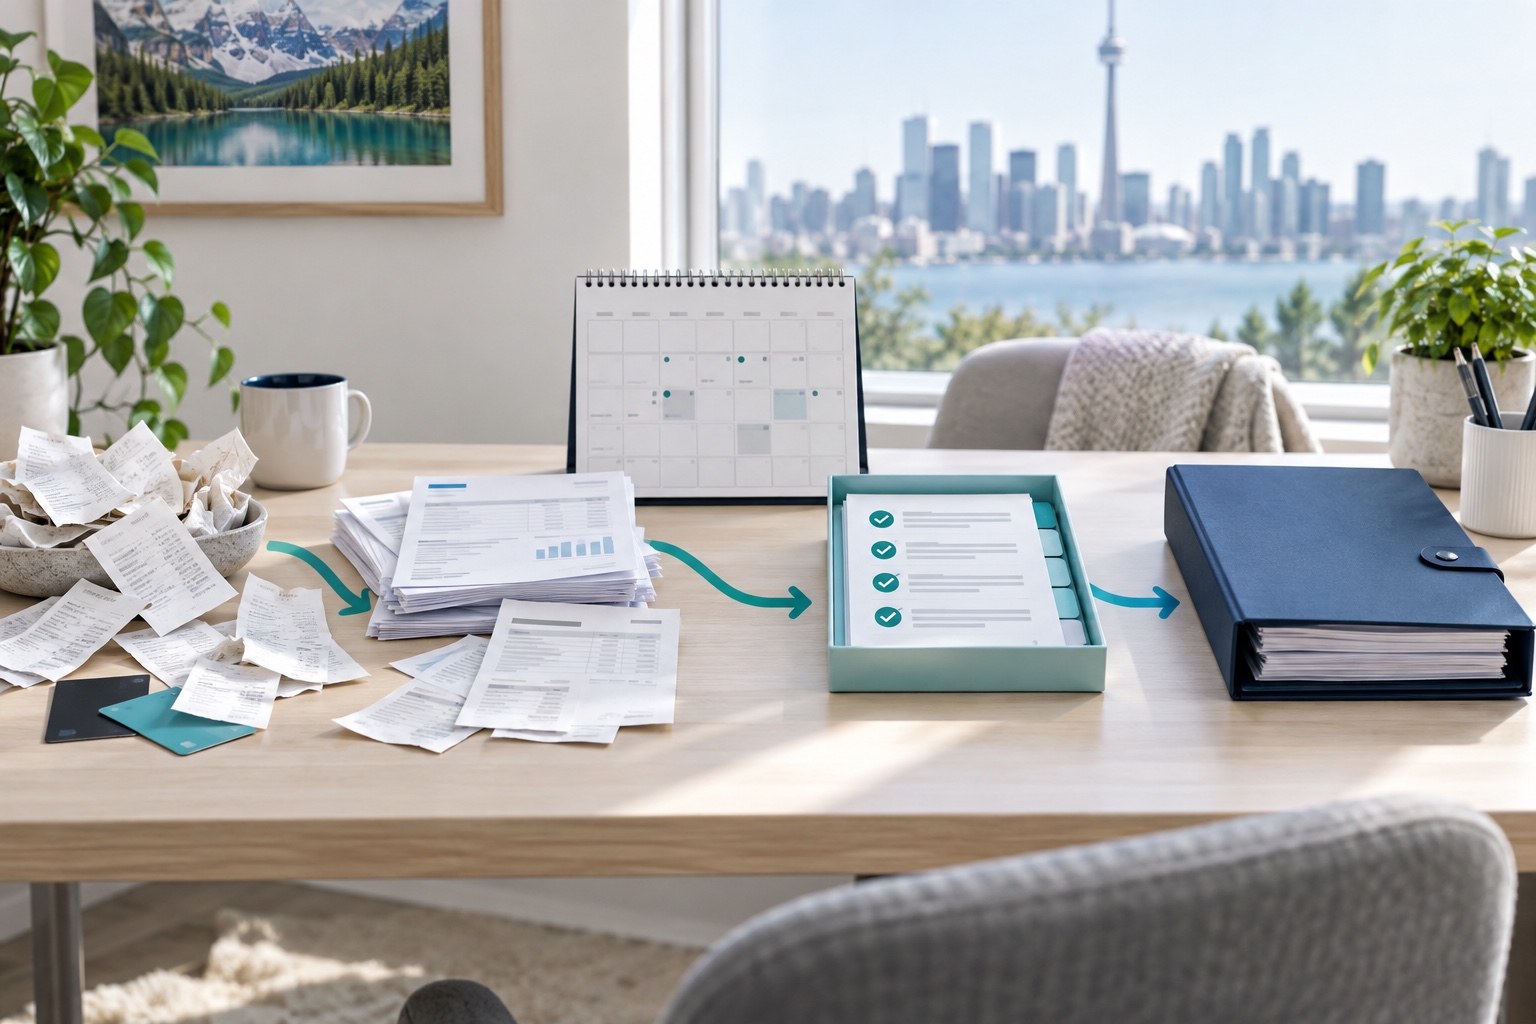
Accountant-ready records are not records with every professional decision already made. They are records that are complete enough to review, organized by Business and period, supported by evidence and honest about what is still uncertain.
A reliable monthly routine makes that possible. Instead of rebuilding the year at tax time, you close each month with a clear package and a short list of exceptions.
The goal is to help your reviewer answer three questions quickly:
1. What happened?
2. What supports it?
3. What still needs a decision?
Start with an exact period and one Business
Choose the month you are reviewing and identify the specific Business.
Do not mix records from several companies merely because they share an owner, card or email inbox. The Canada Revenue Agency says to keep separate records for each business you run.
For each monthly review, write down:
- Business name;
- period start and end dates;
- accounts included;
- reporting currency;
- person completing the review; and
- date the review was completed.
If the period is later reopened, preserve what changed and why rather than silently replacing the completed review.
Step 1: Gather the month’s source records
Collect the evidence connected to business activity during the period:
- sales invoices and other income records;
- purchase receipts and supplier invoices;
- bank and credit-card statements;
- deposit records;
- owner-paid purchases and repayments;
- contractor bills and payment proof;
- mileage and trip records;
- loan or financing documents;
- refunds, credits and reversals; and
- correspondence explaining unusual transactions.
Check the places where documents commonly hide: email, camera roll, glove compartment, shared drive, vendor portal and paper folder.
Avoid placing every file into one unlabelled month-end folder. Attach or name source documents so a reviewer can connect them to the correct transaction.
Step 2: Confirm income records
Review invoices and other income sources for the month.
Ask:
- Were all issued invoices recorded?
- Are invoice numbers sequential where expected?
- Which invoices remain unpaid?
- Were customer payments matched to the correct invoices?
- Are deposits, credits and refunds explained?
- Is any received amount still unidentified?
The CRA says business income records should include the date, amount and source, supported by original documents such as invoices, receipts, deposit slips or contracts.
Do not treat every bank deposit as sales income without context. Transfers, owner contributions, loans and refunds may require different treatment.
Step 3: Review expenses and receipts
For each expense, confirm:
- transaction date;
- supplier;
- total and currency;
- tax shown on the source document;
- Business purpose;
- category or review note;
- payment method;
- owner-paid status, when applicable; and
- attached receipt, invoice or other voucher.
If receipt OCR prepared the entry, compare the suggestions with the original image. Do not assume an extracted amount or tax field is correct simply because the form is complete.
Keep uncertainty visible. A clearly marked missing receipt or unresolved category is safer than a guess that disappears into the final totals.
Step 4: Review owner-paid purchases and repayments
When an owner uses personal funds for a Business purchase, separate two facts:
1. the Business incurred the expense; and
2. the owner paid it.
Confirm that the purchase is recorded under the correct Business and that any repayment is linked without exceeding the eligible balance.
Do not duplicate the expense when recording the repayment. The repayment settles the amount owed to the owner; it does not create the underlying purchase again.
Flag unusual owner transactions for your accountant rather than deciding their final accounting or tax treatment yourself.
Step 5: Review bank and card activity
Use statements to check completeness.
Look for:
- statement transactions missing from the records;
- recorded expenses with no matching payment;
- duplicate imports or entries;
- refunds and reversals;
- transfers mistaken for income or expenses;
- bank fees and interest;
- personal activity in Business accounts; and
- Business activity paid from personal accounts.
If you use a CSV statement workflow, preserve the source file and review proposed matches before confirming them. If you use a direct bank feed, still compare the feed with the official statement and investigate gaps.
Reconciliation is a completeness process. It should not silently create expenses or erase unexplained activity.
Step 6: Review trips and vehicle records
For every Business trip, confirm the information needed by your process, such as:
- date;
- starting point and destination;
- Business purpose;
- distance;
- vehicle;
- Business-use percentage where applicable; and
- related parking, toll or fuel evidence.
Do not invent missing trip purposes at month-end. Ask the person who made the trip while the context is still fresh.
Step 7: Review contractors and bills
Confirm:
- contractor identity and Business scope;
- bill date and amount;
- service description;
- supporting evidence;
- approval status;
- payment status; and
- any question requiring follow-up.
Keep contractor portal access narrow. A contractor submitting a bill should not receive access to the entire Business ledger.
Step 8: Build the open-items list
An accountant-ready package does not hide incomplete work.
Create one short list containing:
- missing receipts;
- unknown deposits or withdrawals;
- unclear Business purposes;
- possible duplicates;
- uncategorized items;
- unmatched bank activity;
- overdue invoices;
- owner repayments awaiting review;
- contractor questions; and
- accounting or tax decisions awaiting a professional.
For each item, record the amount, date, Business, current evidence and next person responsible.
This list can save more review time than another polished summary.
Step 9: Prepare the review package
A useful monthly package may include:
- income and expense detail;
- unpaid customer invoices;
- unpaid contractor or supplier amounts;
- owner-paid expense and repayment detail;
- trip and mileage records;
- relevant statements;
- source attachments or authorized access to them;
- reconciliation exceptions;
- change history for a reopened period; and
- the open-items list.
Use an exact inclusive date range. Label the Business and period on every export. Confirm that private attachments are shared only through an authorized, time-limited method.
Step 10: Complete and preserve the review
Before marking the month complete, confirm:
- [ ] The correct Business and period were reviewed.
- [ ] Income and expenses appear once.
- [ ] Receipts are attached or visibly missing.
- [ ] Statement activity was checked.
- [ ] Owner-paid expenses and repayments are connected.
- [ ] Trips include the necessary context.
- [ ] Contractor and invoice statuses are current.
- [ ] Open questions have an owner.
- [ ] Exports use the intended date range.
- [ ] Sensitive files remain private.
Preserve the completion date and any later changes. A review history is more useful than a checkbox that can be reset without explanation.
What accountant-ready does not mean
Accountant-ready does not mean:
- every transaction has final professional treatment;
- the books are audited or certified;
- tax payable has been calculated;
- a return is ready to file; or
- the software has replaced professional judgment.
It means the evidence and context are organized enough for the next qualified person to work efficiently and ask focused questions.
Where SilaTrail fits
SilaTrail helps owners collect receipts, expenses, trips, invoices, contractor records and owner-paid purchases in Business-scoped workspaces. Monthly Review makes missing information and open items visible before export.
SilaTrail does not certify the books, determine tax obligations or file tax returns. It helps prepare a clearer record trail for review.