Owner-paid expenses
Owner Contribution or Repayment: What Records Should You Keep?
Keep the facts needed to distinguish an owner contribution from repayment of a documented Business expense.
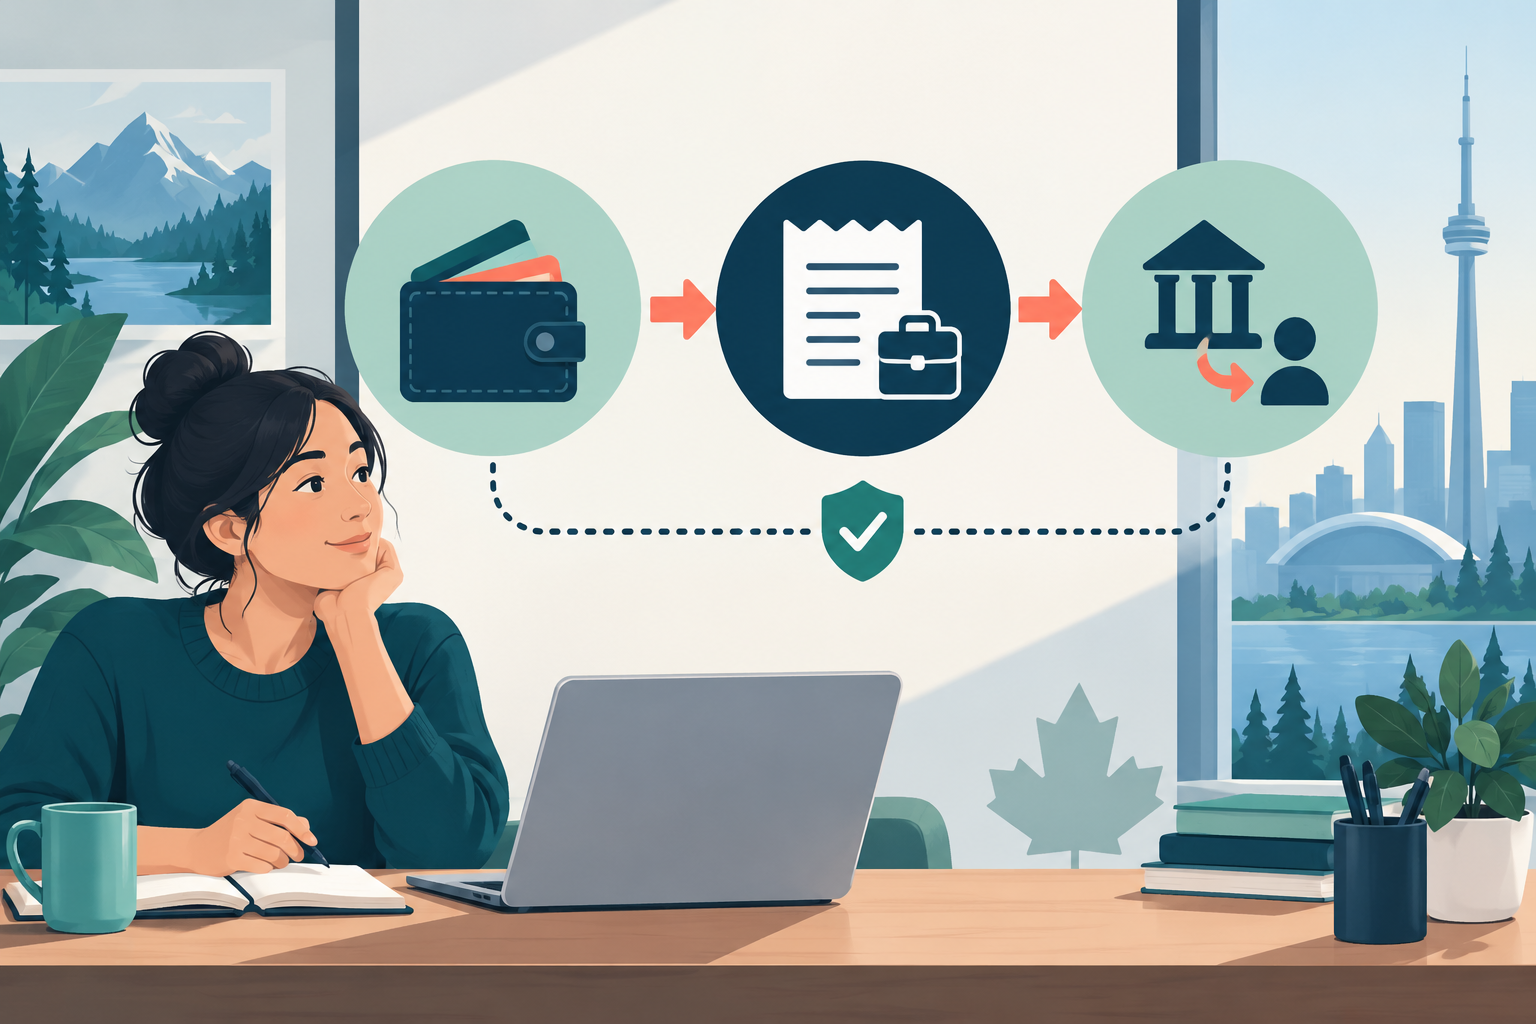
An owner contribution puts value into the Business; an owner repayment returns money connected to a supported owner-paid amount. Record them as different events and keep the documents that explain the source, purpose, authorization and movement of funds.
Those labels are operational, not a tax conclusion. A sole proprietorship, partnership and corporation can require different accounting and legal treatment. SilaTrail does not determine whether an amount is capital, a shareholder loan, a draw, income or a reimbursement.
Document an owner contribution
When an owner transfers money or property into the Business, record:
- date and amount or description;
- contributing owner;
- source and destination accounts;
- stated purpose;
- transfer or deposit evidence; and
- any agreement, resolution or professional instruction relevant to the transaction.
Do not create a supplier expense merely because cash entered the Business. If the contribution later funds expenses, record those purchases separately with their own evidence.
Document an owner repayment
A repayment should connect to an existing supported owner claim or other professionally confirmed balance. Keep the payment date, amount, Business account, recipient, bank evidence and allocation to the open claims.
If only part of the balance is paid, leave the remainder open. If the Business pays more than the supported amount, flag the exception rather than absorbing it into another expense.
Keep the two flows distinct
An owner might contribute $1,000, pay a $200 supplier invoice personally and later receive $200. These are separate records:
1. $1,000 contribution to the Business;
2. $200 Business expense funded personally; and
3. $200 repayment linked to that claim.
Netting them into one number would hide the purchase, funding source and settlement trail.
Review entity-specific treatment
Corporations may need formal records for shareholder transactions, while sole proprietorship records can follow a different equity structure. The CRA’s shareholder-loan guidance is technical and fact-dependent. Use clear source records, then ask an accountant how the entries should appear in the books and returns.
Frequently asked questions
Is every owner transfer a contribution?
No. It may be a loan, repayment, reimbursement or another transaction. Record the facts and obtain professional classification.
Can I net contributions against repayments?
Keep the gross events visible. Netting can hide timing, purpose and unsupported balances.
What documents support a cash contribution?
Keep deposit evidence, the source, owner, date, amount and a written purpose. Entity-specific agreements or resolutions may also be required.
Continue the workflow
Explore SilaTrail’s owner-repayment workflow, monthly review and year-end readiness.
For authoritative context, see the CRA’s Business records, recordkeeping responsibilities and technical Shareholder loans and debts.