Invoices and receivables
How to Track Partially Paid Invoices
Record each payment against the correct invoice while keeping the original value and remaining balance visible.
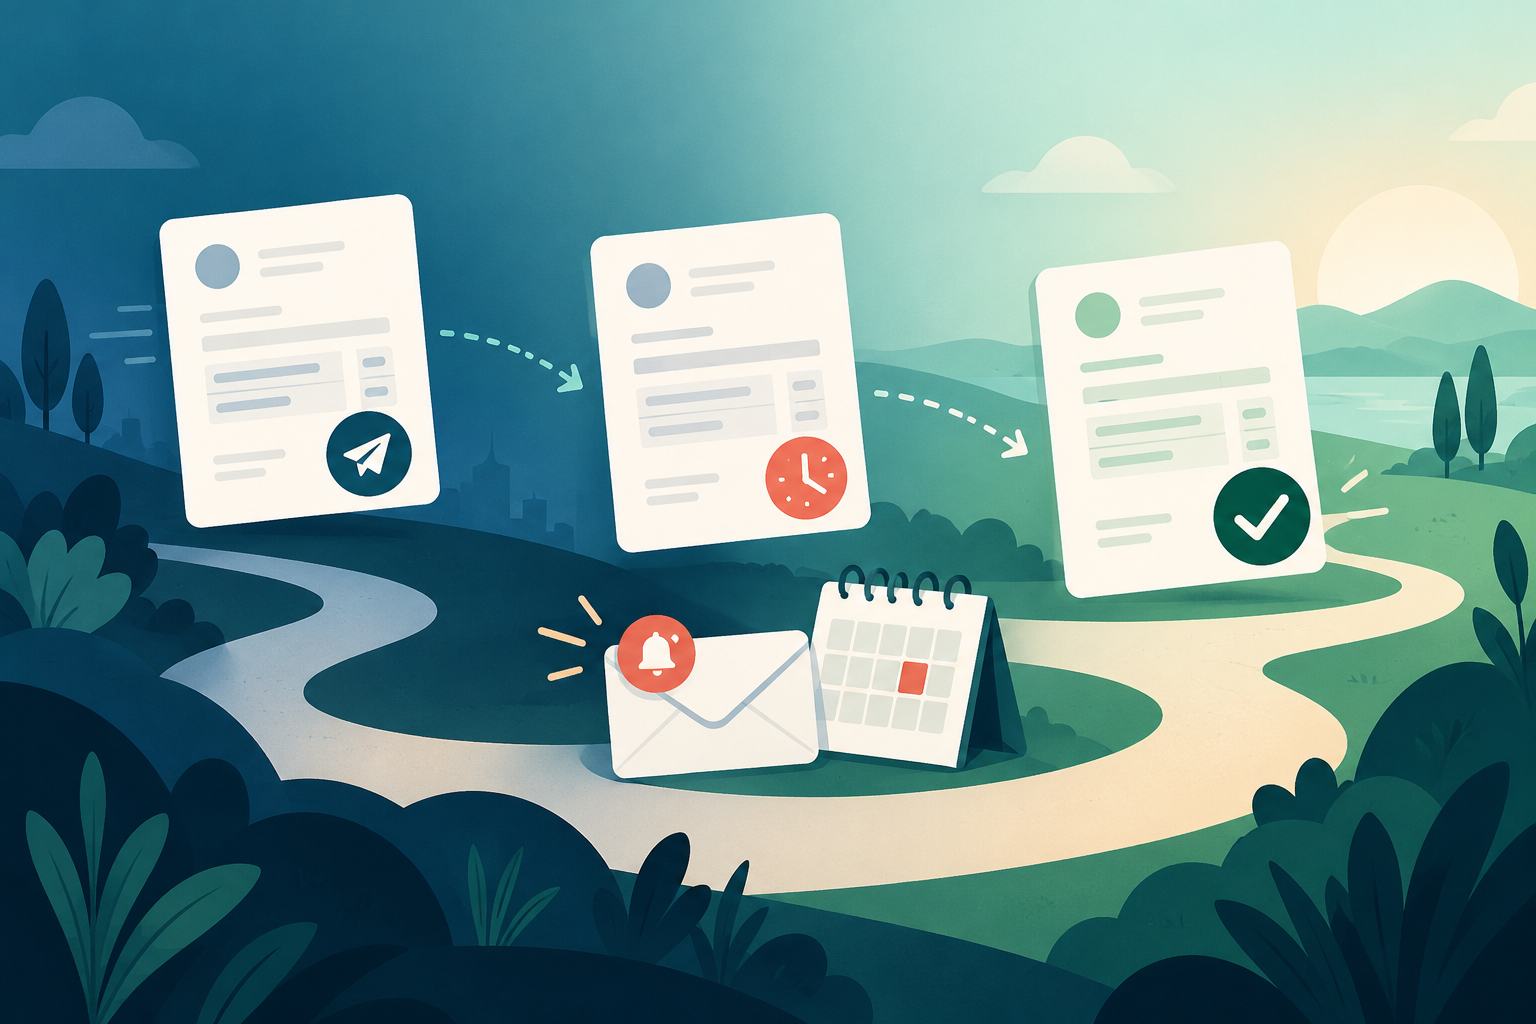
A partially paid invoice is still the original invoice. The customer has paid some of the balance, but the remaining amount stays open until another payment, credit or documented adjustment resolves it.
The safest record preserves the full invoice and records each payment separately.
Keep the original invoice total unchanged
Do not reduce the invoice total to match the first payment. Keep the original amount, issue date, due date, customer and terms. Then attach the payment as a separate event with its actual date, amount, currency and source.
The working balance is:
Original invoice total − linked payments − documented credits = remaining balance
This makes it possible to explain the account without reconstructing it from bank deposits later.
Record every instalment once
For each instalment, keep:
- the date received;
- the amount and currency;
- the payment method or bank reference;
- the invoice number it applies to;
- any customer note about the allocation;
- the person who recorded or reviewed it.
Use customer invoicing to connect payments to the correct invoice. If a payment appears on an imported statement, use bank statement matching to match the movement rather than creating another income record.
Prevent overpayments and duplicates
Before saving a payment, compare it with earlier instalments and the remaining balance. A retry, repeated import or second team member can otherwise record the same payment twice.
A payment larger than the remaining balance needs review. It may be an overpayment, a payment for another invoice or a deposit toward future work. Do not silently change the original invoice to absorb it.
Separate fees, credits and refunds
Payment-processing fees do not normally reduce what the customer paid. Preserve the gross payment and record a supported fee separately. Likewise, use a dated credit or refund record when the business intentionally changes the amount owing.
If the customer disputes part of an invoice, mark the dispute and retain the correspondence. A dispute is not itself a payment or credit.
Show the customer a clear balance
A useful receipt or statement shows:
1. the original invoice amount;
2. each payment and its date;
3. each approved credit or refund;
4. the remaining balance;
5. the next due date or agreed instalment date, when documented.
Avoid exposing internal notes, unrelated bank details or another customer's information.
Preserve evidence for review
The CRA says businesses must keep records of transactions and source documents, including sales invoices and deposit slips. It also requires records that support GST/HST calculations when those rules apply.
Review the CRA pages on business records and GST/HST records.
Partial-payment checklist
Confirm that:
- the original invoice remains intact;
- each instalment has a real date and source;
- no payment or bank match is duplicated;
- the remaining balance recalculates correctly;
- fees, credits and refunds are separate;
- any dispute or special arrangement is documented.
Frequently asked questions
Should I issue a new invoice for every partial payment?
Usually, no. Record the payment against the original invoice unless the underlying agreement requires separate invoices for separate work or milestones.
What if the customer pays several invoices in one transfer?
Allocate the transfer according to the customer's remittance information. The allocations should add back to the bank deposit total.
Can I change the due date after a partial payment?
Only when a documented agreement supports the change. Preserve the original terms and record the revised arrangement so the history remains clear.
Does SilaTrail calculate legal interest or decide tax treatment?
No. SilaTrail records the invoice, payments and balance. It does not determine legal interest, enforceability, revenue recognition or tax timing. Seek professional advice for those decisions.