Banking and reconciliation
How to Review Transfers Without Treating Them as Income or Expense
Recognize internal transfers by tracing both sides and documenting the source and destination accounts.
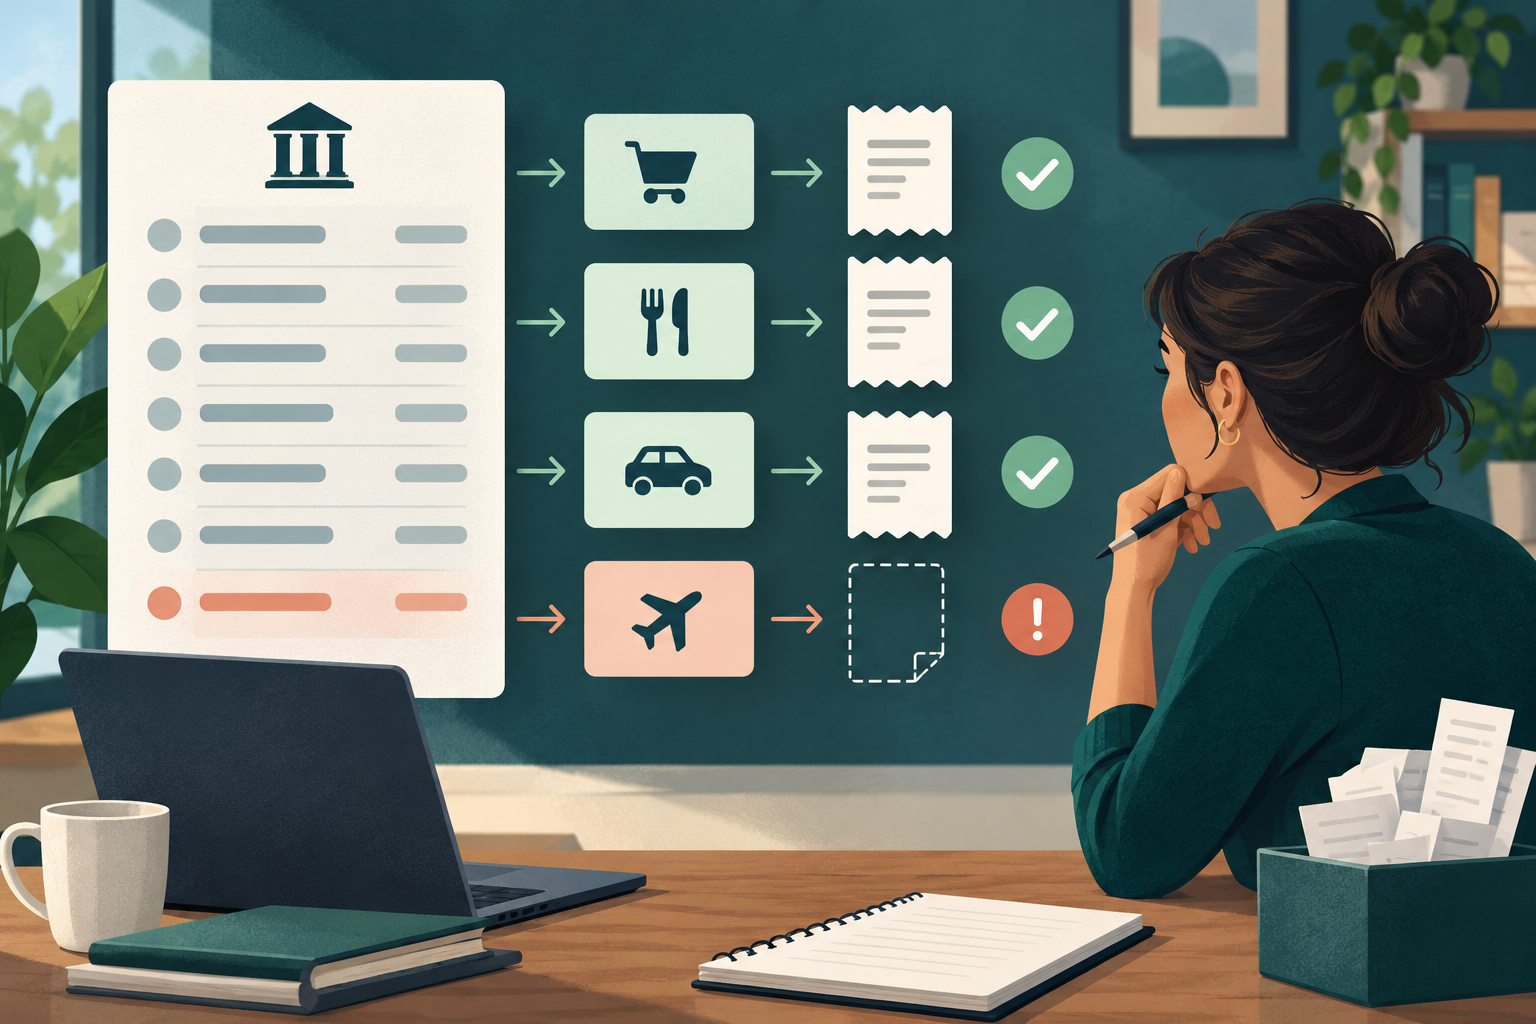
Moving money between accounts does not automatically create income or an expense. A bank review should identify the source, destination and purpose of the movement before assigning any category.
Find both sides of the transfer
For a transfer between accounts owned by the same Business, look for:
- outgoing account and date;
- incoming account and date;
- amount and currency;
- bank reference;
- fees or exchange differences;
- evidence that both accounts belong to the Business.
Posting dates may differ by a day or more. Match the evidence, not only the date.
Link the movement instead of duplicating it
Preserve both statement lines because each belongs to its account. Link them as the two sides of one transfer so the movement does not inflate income or expenses.
Use bank statement matching to match the lines to the transfer record.
Distinguish other kinds of money movement
Not every similar pair is an internal transfer. Review whether the movement is:
- owner contribution or draw;
- repayment of an owner-paid expense;
- loan advance or repayment;
- customer payment;
- supplier refund;
- movement between different Businesses;
- credit-card payment;
- foreign-currency conversion.
Each has different facts and may require professional accounting or tax review.
Use owner repayments when the Business is returning money for a documented owner-paid expense. Do not turn that repayment into a second expense.
Handle inter-Business movements cautiously
A movement between two Businesses is not the same as a transfer between accounts of one Business. Keep records in both Businesses and document the purpose, authorization and expected settlement. Do not use access to one Business to expose or edit the other.
Ask an accountant how to record loans, reimbursements or other inter-entity activity.
Separate fees and currency differences
A bank fee is not part of the transfer principal. Record it separately with the statement evidence. For currency conversion, retain the source amount, destination amount, currencies, applied rate where shown and any fee.
Do not invent a balancing amount when the evidence is incomplete.
Preserve the audit trail
Keep the statement lines, transfer confirmation and any authorization. Record who linked the transfer and when. If the match is later corrected, preserve the reason.
The CRA requires transaction records and supporting documents and says businesses should keep bank statements and separate records for each business. See Business records.
Frequently asked questions
Is a transfer into a Business account always income?
No. It could be an internal transfer, loan, owner contribution or another type of movement. Identify the source and purpose first.
Is a credit-card payment an expense?
The underlying card purchases may be expenses. The payment of the card balance generally moves money to settle the account and should not duplicate those purchases.
What if only one side appears in the period?
Keep it open as a timing or unmatched item and review the next statement. Do not create a fictional second line.
Does SilaTrail decide how a loan or owner transfer is taxed?
No. SilaTrail records relationships and evidence. It does not determine legal form, accounting classification or tax treatment.