Banking and reconciliation
How to Handle Refunds and Reversals in a Bank Review
Connect refunds and reversals to the original transaction while keeping dates, amounts and remaining differences visible.
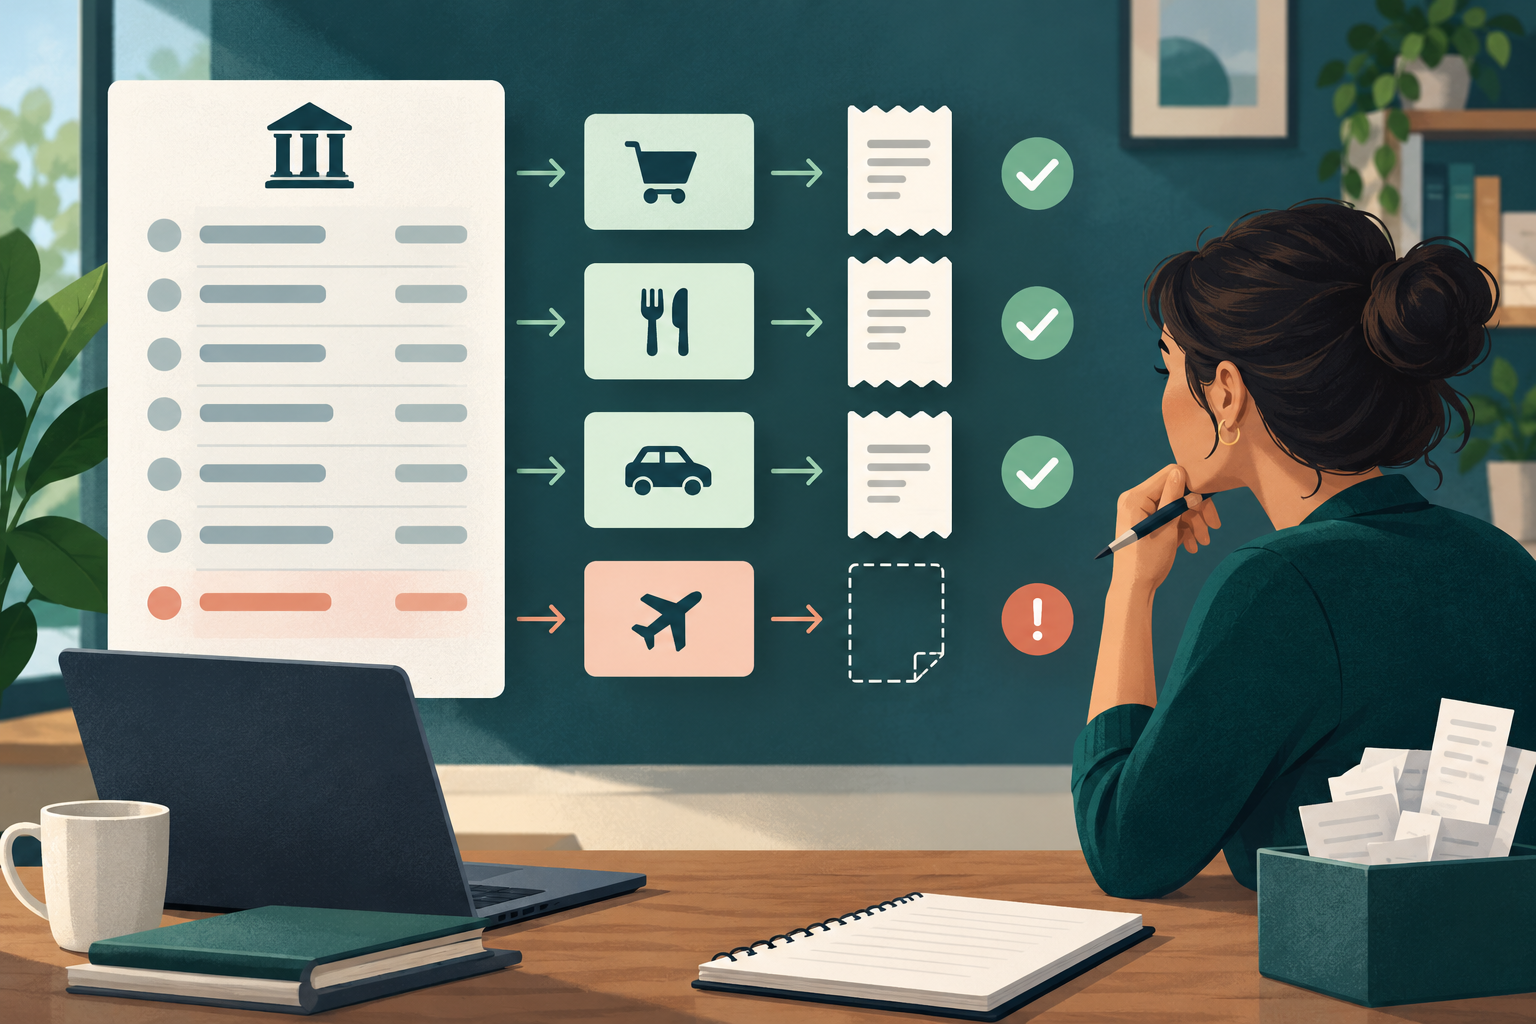
A refund or reversal should explain a change to an earlier transaction. It should not quietly erase the original record or create unrelated income.
During a bank review, preserve the original purchase or payment, record the reversing movement separately and connect the two with the available evidence.
Identify what the bank line represents
A credit on a bank or card statement could be a supplier refund, customer refund reversal, chargeback, corrected bank entry, returned payment or card authorization release. Start with the statement description, date and amount, then compare them with the original transaction and supporting documents.
Do not decide from the positive or negative sign alone.
Keep the original transaction
If a supplier refunded a business purchase, keep the original expense and receipt. Add the refund with its actual date and amount and link it to the purchase. This preserves what happened and when.
If a bank reverses an entry because it was posted in error, retain both statement lines and note the bank's explanation. Do not delete one side simply to make the statement appear cleaner.
Use bank statement matching to connect the statement activity with the existing record rather than creating duplicate income or expense.
Separate full and partial refunds
A full refund may offset the original amount. A partial refund leaves part of the original transaction in place. Confirm:
- original transaction amount and currency;
- refund or reversal date;
- amount returned;
- supplier, customer or bank reference;
- reason for the adjustment;
- remaining amount after the adjustment.
Do not change the original amount to match a partial refund.
Review fees and exchange differences
A reversal may not equal the original amount because of processing fees, foreign exchange or only part of the transaction being corrected. Record supported fees separately and leave unexplained differences open for review.
Never invent an exchange rate or fee to force a match.
Preserve supporting evidence
Keep the original receipt or invoice, refund confirmation, correspondence and relevant statement lines. The CRA says business records should include transaction evidence such as receipts, invoices, bank statements and cancelled cheques. See Business records and Keeping records.
Month-end review checklist
Before closing the item, confirm that:
1. the original transaction remains visible;
2. the refund or reversal is recorded once;
3. the two records are linked;
4. the net amount agrees with the statement;
5. fees or currency differences are separate;
6. the treatment is flagged for professional review when uncertain.
Carry unresolved items into monthly review.
Frequently asked questions
Is every bank credit income?
No. A credit may be a refund, transfer, loan, owner contribution or correction. Identify the source before classifying it.
Should a refund use the original transaction date?
Record the refund using the date it actually occurred while keeping the original transaction date unchanged.
What if the supplier refunds a different card or account?
Link the refund to the original purchase and record the account that actually received it. The relationship matters even when the bank accounts differ.
Does SilaTrail decide the tax treatment?
No. SilaTrail records and links the evidence. It does not decide GST/HST adjustments, income recognition or deductible amounts. Ask a qualified professional when treatment is uncertain.